


- Bitcoin treasury firms are using record debt to buy Bitcoin, raising concerns about high leverage.
- Analysts warn this could trigger forced selling during market downturns.
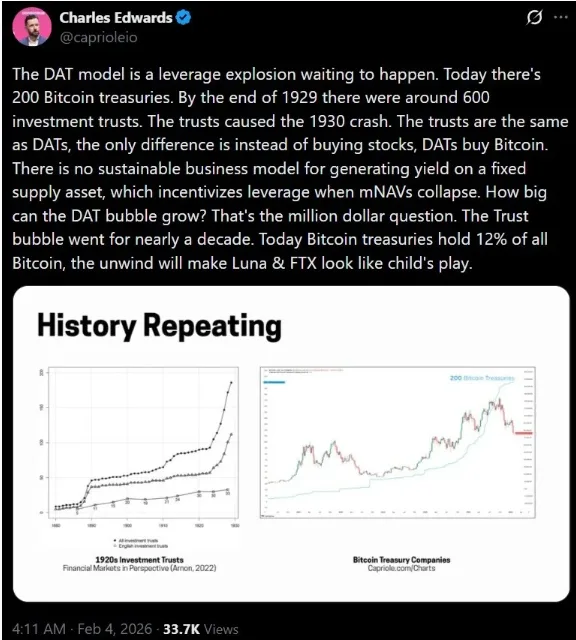
Bitcoin treasury companies are under fresh scrutiny after concerns emerged that rising debt levels could make the sector more fragile than it appears. According to Capriole Investments founder Charles Edwards, many firms accumulating Bitcoin are increasingly relying on borrowed money, creating what he describes as an unsustainable structure built on leverage.
His warning revives earlier concerns about the digital asset treasury model, especially as more companies adopt aggressive borrowing strategies to expand their Bitcoin holdings.
Debt-Fueled Bitcoin Buying Reaches New Highs
Edwards argues that Bitcoin treasury companies are now “levering up at record rates” to finance continued accumulation. These firms, often referred to as digital asset treasuries, raise capital through debt or equity issuance and use the proceeds to buy Bitcoin for their balance sheets.
The approach can amplify gains when Bitcoin prices rise. However, it also increases financial pressure when prices fall, especially for companies that must service debt regardless of market conditions.
Edwards warns that this cycle is becoming more extreme as more players enter the market and competition for Bitcoin exposure increases.
The 1929 Comparison and Structural Risks
A major part of Edwards’ argument is his comparison between today’s Bitcoin treasury companies and leveraged investment trusts from 1929. He suggests that the growing number of crypto treasury firms mirrors past market structures that collapsed under excessive borrowing and speculation.
He estimates there are now around 200 Bitcoin treasury companies, and argues that their combined leverage could trigger a chain reaction during downturns. In such a scenario, falling prices could force companies to sell Bitcoin to meet obligations, pushing prices even lower.
This cascading effect is central to his concern that the current structure may not hold under stress.
The “Fake Yield” Debate
Edwards also criticizes how some treasury firms present their performance metrics. Many companies highlight growth in Bitcoin per share as a sign of success. However, he argues that this “yield” is often not generated through operational income but through debt issuance or equity dilution.
In his view, this creates an illusion of sustainable returns. He describes it as a system that only works while capital markets remain open and Bitcoin prices continue rising. Once liquidity tightens, he warns, the same structure could reverse and expose underlying weaknesses.

Signs of Strain Already Emerging
Recent market data suggests growing pressure on the Bitcoin treasury sector. Reports indicate that buying activity outside major holders has slowed sharply, with only a small amount of new accumulation recorded over recent months.
One dominant player, Strategy Inc, now holds a large share of corporate Bitcoin reserves, estimated at around three-quarters of all corporate holdings. This concentration highlights how dependent the sector has become on a few major balance sheets.
At the same time, some companies continue to expand aggressively through debt. Japan-based Metaplanet has used repeated debt financing rounds, including zero-coupon bonds, to grow its Bitcoin position while targeting long-term accumulation goals. However, it has also reported significant financial losses alongside its expansion.
Borrow-or-Sell Pressure Intensifies
A key concern now facing Bitcoin treasury firms is liquidity management. Companies must balance ongoing costs such as debt servicing, dividends, and operational expenses without reducing their Bitcoin exposure.
This creates what analysts describe as a “borrow-or-sell” dilemma. Firms must either continue raising debt or risk selling part of their holdings during downturns. Both options introduce pressure into the market structure.
If multiple firms face this decision at the same time, selling pressure could intensify quickly.
Market Weakness Adds to Concerns
The warning comes during a period of heightened volatility for Bitcoin. The asset recently experienced one of its sharpest weekly declines since the fallout of the FTX collapse in 2022, briefly falling below key price levels as ETF outflows increased.
In such conditions, highly leveraged treasury companies tend to face the most stress first. Their balance sheets are more sensitive to price swings, and forced liquidations become more likely when credit conditions tighten.
What Happens Next for Bitcoin Treasuries
The future of Bitcoin treasury companies now depends heavily on market direction. If prices recover strongly, leverage could once again appear as an effective strategy for scaling exposure and returns.
However, if weakness continues, the same leverage could accelerate downside pressure across the sector.
Edwards’ warning highlights a growing divide in how the market views these firms. Some see them as innovative financial vehicles for Bitcoin exposure. Others see them as highly leveraged structures that may struggle under prolonged stress.
For now, the sector remains a key part of corporate Bitcoin adoption, but also one of its most closely watched risk factors.
DISCLAIMER:
The views and opinions expressed herein are solely those of the author and do not necessarily reflect the views of the publisher. The publisher does not endorse or guarantee the accuracy of any information presented in this article. Readers are encouraged to conduct further research and consult additional sources before making any decisions based on the content provided.